Biweekly Budgeting: A Step-by-Step Guide
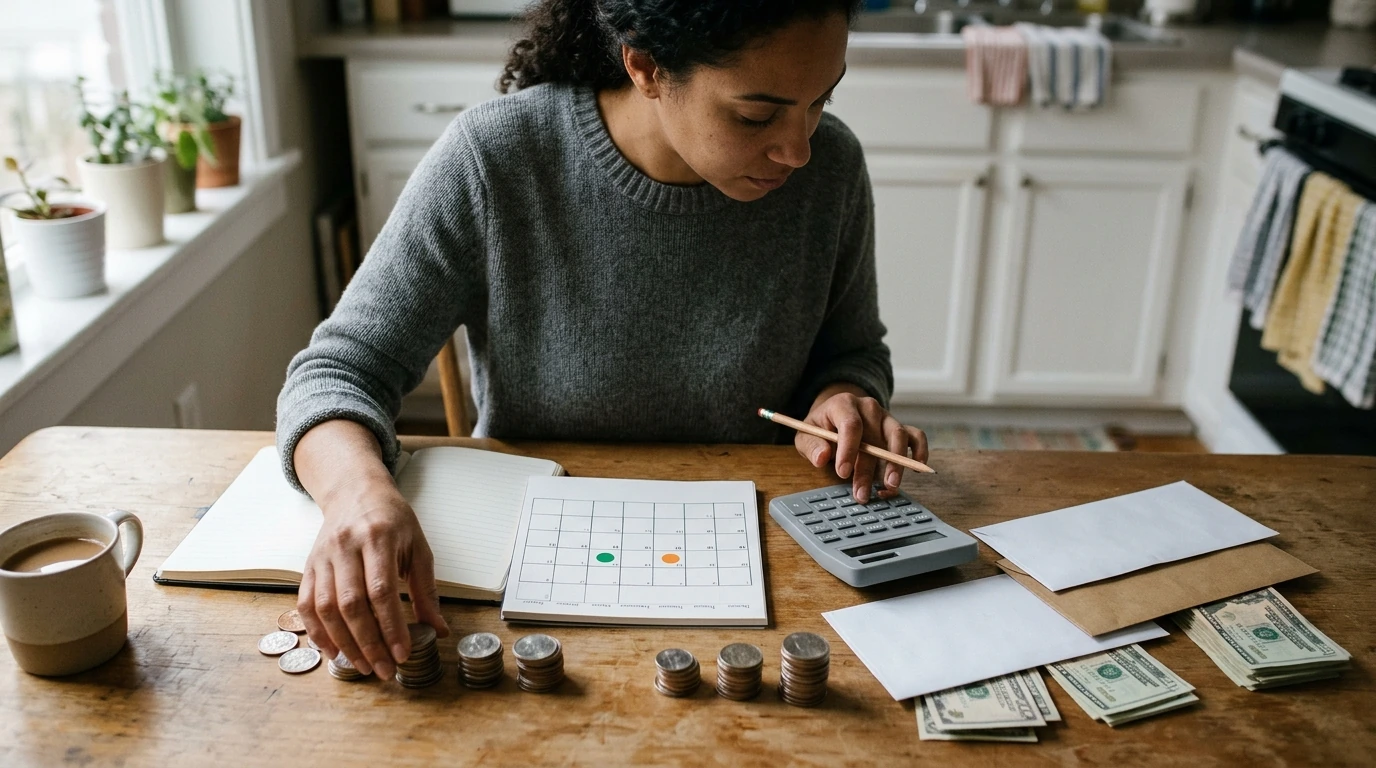
A biweekly budget puts your paycheck dates at the center of your financial plan. Instead of looking only at monthly totals, you decide what each paycheck needs to cover before the next one arrives. That can help you plan for bills, everyday expenses, and savings without losing sight of timing.
You do not need a perfect spreadsheet to begin. A calendar, a list of expenses, and an honest look at your take-home pay can give you a useful starting point. Our team recommends reviewing the plan regularly so it can change along with your needs.
How a Biweekly Budget Works
If you are paid biweekly, you receive a paycheck every two weeks. That generally adds up to 26 paychecks a year. Most months have two paydays, while two months typically have three.
Biweekly pay is different from being paid twice a month. A twice-monthly schedule usually means 24 paychecks a year, often on set dates such as the first and fifteenth. With biweekly pay, your payday stays on the same day of the week, but its calendar date changes.
A paycheck-by-paycheck plan accounts for those changing dates. For example, if rent is due on the first, you might reserve part of it from each of the two paychecks before the due date. The goal is to have the money ready when the bill arrives, not just to have enough income on paper over the course of a month.
Build Your Budget One Paycheck at a Time
Start by writing down your upcoming payday dates and the amount you expect to take home after taxes and other deductions. Next, list your bills, their amounts, and their due dates. Include housing, utilities, insurance, debt payments, and subscriptions, along with essentials such as groceries and transportation.
Then give each paycheck a job. Assign money to bills and essential expenses first. After that, decide what you can put toward savings and flexible spending, such as dining out or entertainment. If possible, leave a small buffer for costs you did not anticipate.
The following example assigns a $1,500 paycheck. Your amounts will depend on your bills, household, and priorities.
| Category | Amount | Purpose |
|---|---|---|
| Bills and housing | $750 | Set aside for upcoming fixed expenses |
| Groceries and transport | $350 | Cover essential spending until the next payday |
| Savings | $150 | Build an emergency cushion or save for a goal |
| Flexible spending | $150 | Cover discretionary purchases |
| Buffer | $100 | Allow for unexpected costs |
| Total | $1,500 | Assign the full paycheck |
Use your calendar to check the order of paydays and bills. If a $600 bill is due before your next payday and you have already saved $300 for it, the current paycheck needs to supply the remaining $300. Keep the money reserved for that bill rather than counting it as available spending money.
If your planned expenses exceed your income, adjust before payday. Reduce flexible spending where you can, revisit savings contributions, and look for bills you can lower. If essentials still do not fit, contact providers or creditors early to ask about payment arrangements. Consumer.gov’s budgeting guidance offers another starting point for comparing income and expenses.
Plan for Irregular Expenses and Extra Paychecks
Some expenses are predictable even though they do not arrive every pay period. Annual fees, gifts, car maintenance, and medical costs can disrupt a budget if you wait until they are due. Estimate what you will need and divide it across the paychecks you expect before then.
For example, if you want to save $240 for an annual fee and have 12 paychecks before it comes due, setting aside $20 per paycheck reaches that target. You can keep these amounts in separate savings categories or track them together in one account.
Mark the months with a third paycheck on your calendar, too. Those paychecks can help you build a buffer, make progress on debt, or fund an upcoming expense. They are not automatically spare money, though: check the bills and essentials due before the following payday first. Once those obligations are covered, choose a purpose for what remains.
Keep Your Budget Working
Before each payday, compare your plan with what you spent. If groceries cost more than expected, adjust the next allocation rather than assuming the same amount will work. You can also move money between categories when priorities change, as long as you protect funds already needed for bills.
If your income varies, use a cautious take-home estimate and prioritize housing, food, utilities, transportation, and required payments. When a paycheck is larger than expected, consider using part of the difference to prepare for a leaner pay period. The Consumer Financial Protection Bureau’s budgeting resources can help you explore ways to track and manage your money.
For a step-by-step starting point, our Biweekly Budgeting: How It Works guide is listed at $8.99. If travel is one of the goals you are saving toward, our travel deals with AI digital ebook is another option to explore. Set a travel savings target that fits alongside your essential bills rather than relying on an extra paycheck to cover everything.
FAQ
Is biweekly pay the same as being paid twice a month?
No. Biweekly pay arrives every two weeks and usually results in 26 paychecks per year; twice-monthly pay usually results in 24.
How do I budget monthly bills when I am paid every two weeks?
Track each bill’s due date and set aside money from the paychecks that arrive before it is due. Check your calendar for timing gaps so the full amount is available when you need it.
What should I do with a third paycheck in a month?
First check the bills and essential expenses due before your next payday. Then consider using available funds for a buffer, savings goals, or debt payments.



Leave a comment